 Andrey Shubin
In an environment defined by energy volatility and geopolitical uncertainty, the ability to understand how disruptions ripple across commodities is no longer optional. Recent tensions have placed global energy chokepoints under increased scrutiny; particularly the Strait of Hormuz, a transit point for nearly 20% of global LNG trade and a critical risk factor for European energy security.
As Europe becomes increasingly reliant on LNG to replace legacy pipeline flows, any disruption to global supply has immediate implications for both gas and power markets. But while market forward curves react quickly to these risks, they do not always reflect how the physical system will respond.
To explore this dynamic, we used PLEXOS® to perform a fundamental cross-commodity stress test: how would a 30% reduction in global LNG supply impact European gas and power prices through 2028? By modeling physical supply, demand, and infrastructure constraints, this approach provides a clearer view of how the system is likely to rebalance—and what that means for analysts making planning and trading decisions today.
How was the LNG disruption scenario modelled?
To support this analysis, we deployed two integrated datasets:
- Energy Exemplar’s European Gas Fundamental Model: This dataset models every European country as an individual pricing hub, capturing all cross-border pipeline connections and LNG regasification terminals.
- Energy Exemplar’s Medium-Term Pan-European Power Model: An operational model calibrated for continental forward price forecasting. We utilized a Monte Carlo simulation with 10 weather scenarios derived from the Pan-European Climate Database (PECD).
What did the Strait of Hormuz disruption scenario assume?
We applied a 30% reduction in global LNG supply to European hubs from March 2026 to March 2027. This acts as a proxy for a significant blockade at the Straits of Hormuz—a transit point for nearly 20% of global LNG trade. We updated the model with recent AGSI storage data and 15th March 2026 price benchmarks.
How did the LNG disruption affect European gas prices and physical adequacy?
A common limitation in modeling is treating gas prices as a fixed input. In this study, we first run the gas model as a standalone fundamental simulation. We relaxed gas storage constraints—subject only to physical limitations—allowing the model to draw down inventory to meet demand across the electric, residential, and commercial sectors.
Findings: Physical Adequacy
Despite the massive 30% reduction in LNG availability, the model showed no unserved demand. While storage depletion occurs, it is mitigated by sufficient pipeline imports and the natural decrease in consumption as the winter heating season concludes.
Figure 1: PLEXOS®30% LNG reduction gas price forecast compared with market expectations
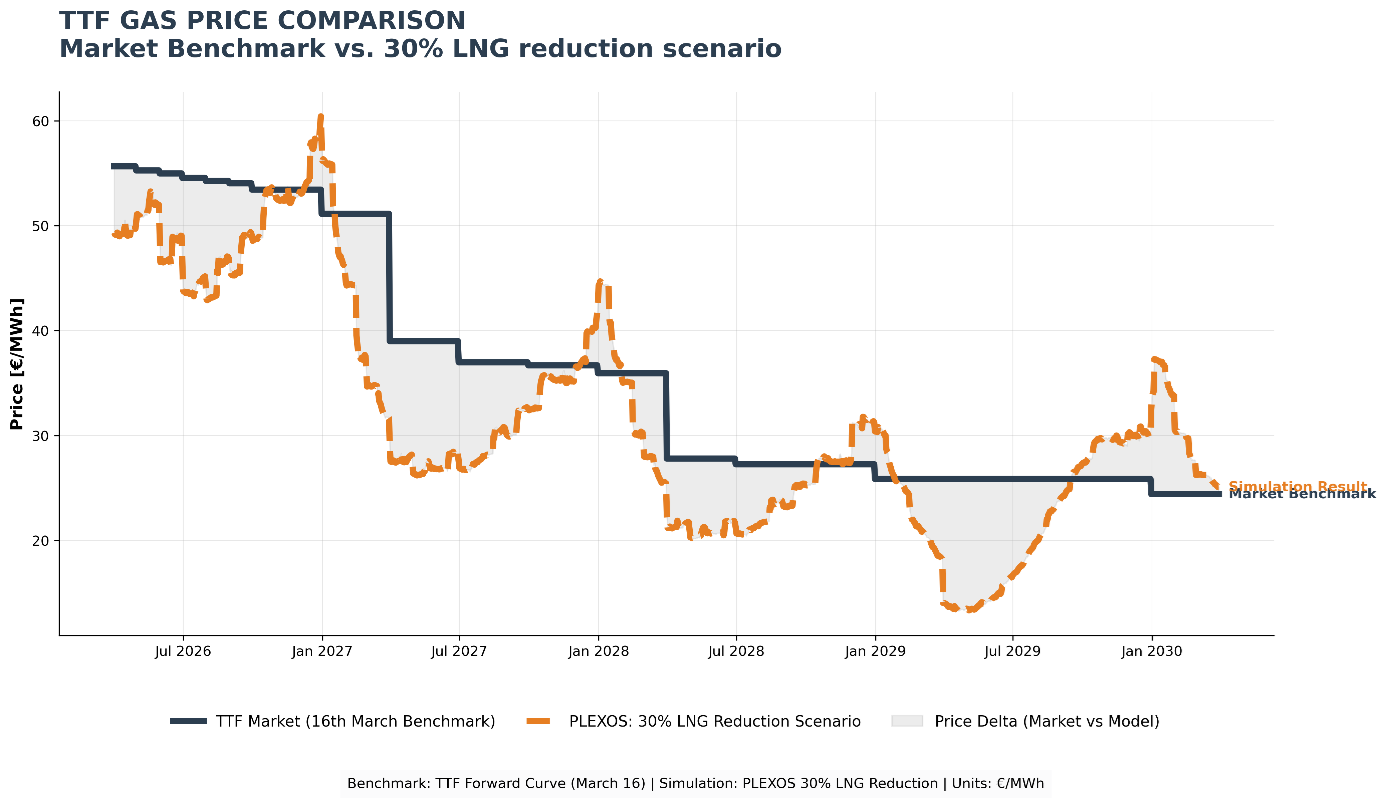
Comparison of the fundamental gas price (derived from 30% LNG shock) against the March 24th Market Forward curve.
Fundamental Price Impact
Because the model identifies that physical demand can still be met, the resulting fundamental price forecast is bearish compared to current market expectations. While expensive LNG sets marginal prices during winter peaks, pipeline imports set the marginal level during shoulder seasons. This suggests that current market forwards may carry a significant risk premium. This highlights a critical risk: relying on forward curves alone may lead to overestimating sustained price levels, particularly when the physical system has the capacity to rebalance more efficiently than market sentiment implies.
How did the LNG disruption affect European power-price forecasts?
In the second stage of the analysis, the fundamental gas prices derived in Part 1 were used as the primary input to simulate European power prices for the next three years. We compared three distinct gas price inputs:
-
30% LNG Reduction Scenario (Fundamental)
- Base Case (March 18th Gas Forwards)
- Pre-Conflict Baseline (February 24th Gas Forwards)
Germany (DE) Findings
For 2026, the increase in the German power price forecast is significant, particularly in Q2 and Q4, as gas frequently sets the marginal price. However, the fundamental 30% LNG reduction scenario is lower than the current market Base Case. Toward the end of the forecasting period (2028), power prices drop below pre-conflict expectations as the gas model expects the market to absorb the shock through supply growth and fuel switching. This suggests that short-term price signals may overstate long-term structural impacts, an important consideration for asset valuation, hedging strategies, and medium-term planning decisions.
Figure 2: DE Power Price Trends
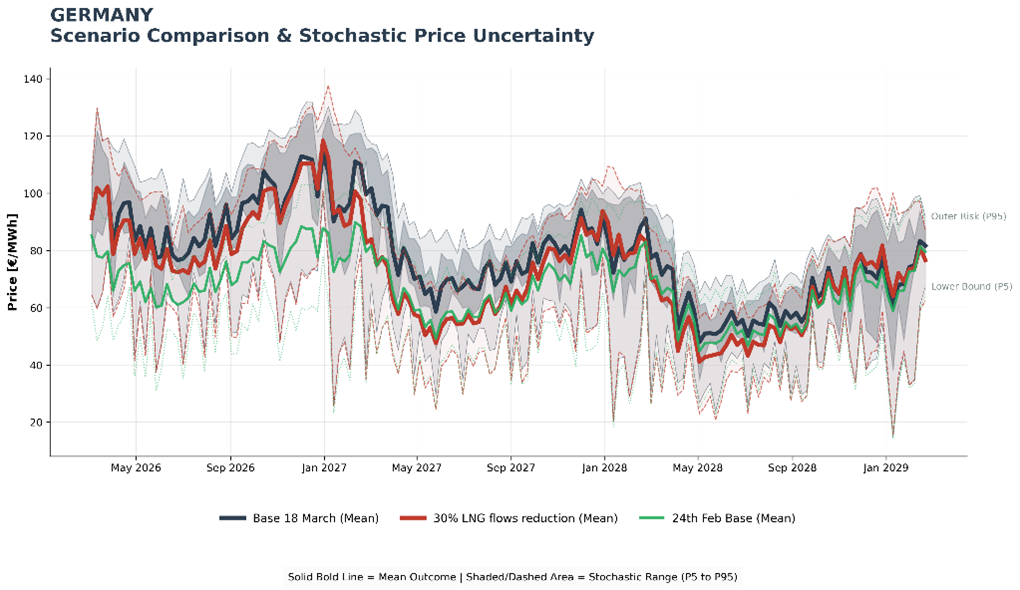
German power price projections across three scenarios, illustrating the market's expected absorption of the supply shock by 2028
United Kingdom (UK) Findings:
The UK experienced a more dramatic increase than Germany due to its higher natural gas dependency. The Base Case (employing market forwards) showed a relative increase exceeding 30% for the following three quarters. Like the continental market, the fundamental LNG reduction scenario is bearish in the long term compared to current forwards.
Figure 3: UK Power Price Trends
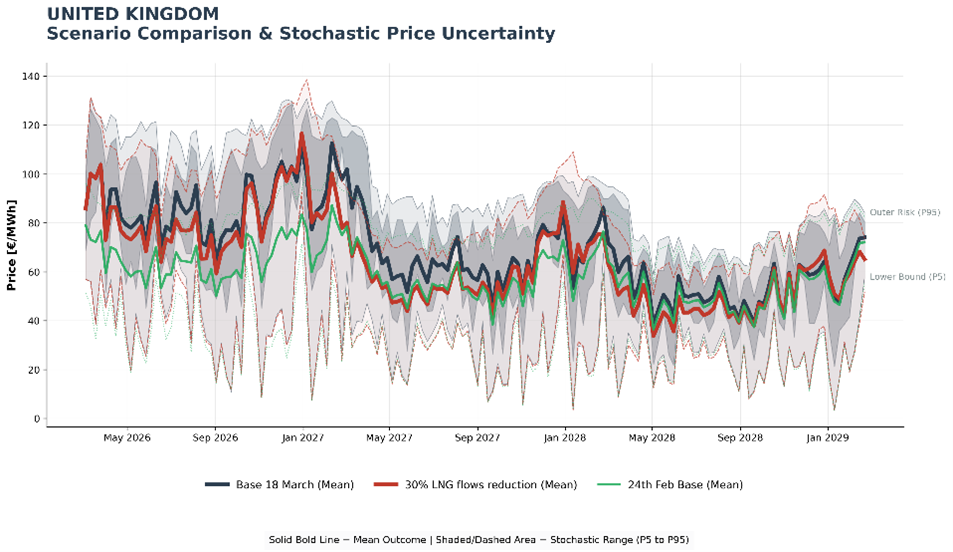
The UK's high gas-to-power dependency results in more volatile price deltas compared to the more diversified continental European grid.
What does this scenario show about cross-commodity modelling?
This analysis reinforces a fundamental truth: a sound power price forecast cannot exist in a vacuum. While many analysts rely on power-only models and external gas price inputs, this approach can miss how the physical system responds under stress.
By modeling gas and power together, we can move beyond static assumptions and simulate how supply, demand, and infrastructure interact in real conditions. In this case, even under a 30% LNG disruption scenario, the European gas system can rebalance through a combination of storage drawdowns, pipeline imports, and seasonal demand shifts.
That physical adequacy has direct implications for planning decisions. While market forwards reflect risk and uncertainty, they may overstate long-term price impacts when the underlying system has the flexibility to absorb the shock. A fundamental approach provides a clearer view of where and when those risks are likely to materialize, and where they are not.
For analysts and modelers, access to cross-commodity simulation in a platform like PLEXOS® enables a more proactive approach. Instead of treating gas prices as a fixed input, they can be derived from the system itself—allowing users to anticipate how disruptions propagate across both gas and power markets, test infrastructure limits, and evaluate the conditions under which the market rebalances.
Ultimately, the ability to model the full energy value chain—from upstream gas supply to downstream power prices—provides a more complete understanding of the forces that will settle the market. In an environment defined by supply uncertainty and geopolitical risk, that integrated view is what allows analysts to distinguish between short-term market signals and the underlying system dynamics, in turn allowing them to act with greater confidence.
What FERC and USEA Conferences Reveal About Energy Reliability
 Rob Homer : November 10, 2025
Key FERC and USEA conference insights on data-center demand, gas-electric coordination, market design, and integrated reliability planning.
Evolution of European Gas Markets
 Dr. Kristo Helin : December 16, 2022
By unpacking the history of Europe's Gas market, Energy Exemplar's Dr. Kristo Helin shows why today's gas market is more sensitive than ever before.
How Data Center Growth Is Reshaping Power-System Planning
 Team Energy Exemplar : January 8, 2025
Learn how rapid data-center growth is reshaping generation, transmission, interconnection, and energy-planning decisions across the power system.